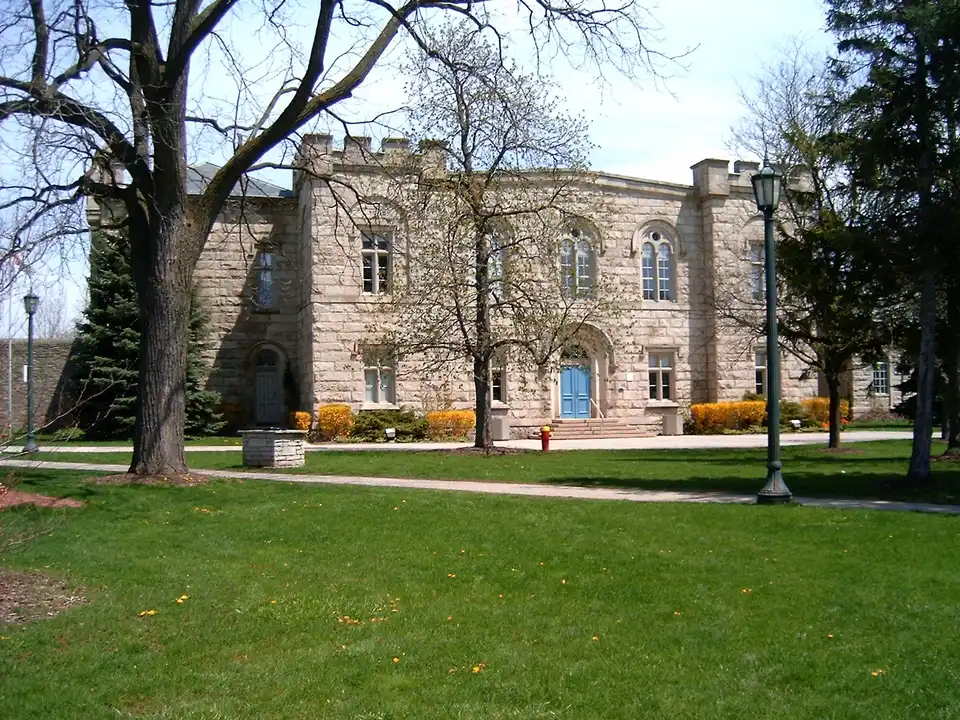
Old Milton is the town’s original core
Old Milton is the part of town that grew up around Main Street, Mill Pond and Sixteen Mile Creek. Milton became a town in 1857 (Wikipedia, as of October 2026), and it started around Jasper Martin’s grist mill, whose dam made Mill Pond.
Old Milton was built mainly between 1850 and 1890, according to Wikipedia’s neighbourhood table (a secondary source, so treat the years as approximate). Its rough edges are Bronte Street South, the CP Rail tracks, Thompson Road and the Robert Street to Nipissing Road line.
That age makes Old Milton rare in a young town. Statistics Canada’s 2021 Census found 73% of Milton homes were built in 2001 or later, and only 18.9% before 1981.
Most of those older homes sit in Old Milton and the ring built after it: Mountainview (the first area built after the 1949 sewage plant), Fallingbrook (1960s), Dorset Park (registered in 1973) and the first phases of Timberlea (late 1970s).
The Town’s own rules for mature neighbourhoods
The Town of Milton studied these older areas in its Mature Neighbourhoods Character Study. It led to By-law 081-2020 for the Downtown Character Area and Martin Street, and By-law 077-2021 for Mountainview and the rest of residential Old Milton.
If you’re thinking about an addition, ask the Town’s planning staff what those by-laws allow before you set a budget. It’s easier to size the amount you take once you know what you can build.
How an older house changes the appraisal
Every reverse mortgage needs an appraisal. The appraiser visits your home once, and the fee is usually about $350. The value they set decides the most you can borrow.
On an older house, condition counts for more. The appraiser looks at size, location and recent nearby sales, as on any home, and also at the state of the roof, foundation, windows and main systems. Statistics Canada’s 2021 Census counted 1,075 Milton homes (2.7%) needing major repairs.
Here is how condition usually plays out:
- Good repair: the appraisal goes ahead like any other, and the value decides your ceiling.
- Some repairs needed: a lender can sometimes hold back part of the money until the work is done, so the repair is paid from the mortgage itself. This is typically called a holdback.
- Serious disrepair: a home in major disrepair usually has to be fixed first, because no lender will go ahead on it as it stands.
Upkeep stays your job for as long as the mortgage runs, along with property tax and home insurance. There are no required monthly mortgage payments, but letting the home fall into serious disrepair is one of the few things that lets a lender act.
Heritage rules in Old Milton
The Town of Milton’s heritage pages (October 2026) show no heritage district. The Town protects buildings one at a time, either by designating them or by listing them on a register. The downtown is a planning “Character Area”, not a heritage district.
A designated home needs a Town heritage permit for additions, window and door changes, porches, decks, fences, trim, roofing or cladding changes, and painting the outside. Routine maintenance, re-roofing in a similar material and colour, plain eavestroughs, repointing and chimney repair need no permit.
A listed home (on the register but not designated) needs no heritage permit for alterations. The Town only asks for 60 days’ notice before a demolition.
That is about to change. The Town says that from January 2027 its register will hold only designated properties, and more than 900 listed properties will be removed. It is encouraging owners to consider designating voluntarily.
If you plan to use reverse mortgage money on a designated home, apply for the heritage permit first. Then the amount you take, the permit and the contractor’s start date can all line up. Renovations for Milton seniors covers permits and tax credits in more detail.
What the numbers could look like for an older home
TRREB publishes no benchmark for Old Milton alone. For all of Milton, the TRREB MLS® Home Price Index put a typical detached house at $1,149,000 in September 2026, down 6.46% from a year earlier. Older homes in Old Milton vary widely around that figure, which is why the appraisal decides.
Say an Old Milton homeowner, 75, owns a detached brick house. If it appraised at the $1,149,000 benchmark, the most she could borrow would be about $664,000. If its age and condition brought the appraisal to $900,000, her ceiling at 75 would be about $520,000.
She can take less than that. She pays interest only on what she actually takes, and her home’s value usually grows too, and that growth stays hers. You can try your own numbers in the Milton reverse mortgage calculator.
Staying in your home near Main Street
Old Milton suits someone who wants to stay in their home for the long run. Much of what matters is a short trip away.
- Main Street: the Milton Chamber of Commerce runs a farmers’ market on Saturday mornings, 8 a.m. to noon, from mid-May (Milton Farmers’ Market, 2026).
- Town Hall, 150 Mary Street: Milton homeowners 65 and older apply here for Halton Region’s older-adult property tax deferral. The 2026 intake has closed, and Halton says a new form comes in spring 2027.
- Civic Square: phase one was approved on July 14, 2025: a pedestrian area between the Town Hall forecourt and Main Street East (Town of Milton, Downtown Study).
- Martin Street: Aspira Martindale Gardens, a 75-suite retirement residence, sits at 45 Martin Street near Main Street East (HIP Halton directory, June 2026). It’s a retirement residence, not a long-term care home.
- Seniors’ memberships: the Town’s 55+ membership costs $25 a year at 65 to 84 and is free at 85 and older (Town of Milton, October 2026).
If you join Halton’s tax deferral, you would choose between it and a reverse mortgage, because a reverse mortgage pays off any deferred tax when it closes. Property tax help for Milton seniors compares the two, and Milton seniors’ services lists the rest.
Richard goes over your situation by email, phone or video call, and a son or daughter can follow along on the emails. You get a recommendation based on your situation, even if it’s not a reverse mortgage. More on how that works is on the Milton seniors’ mortgage broker page.